UK Budget 2026: The Gambling Tax Squeeze Facing Britain's Bookmakers
Stephen Tabone analyses the UK's latest gambling tax increases, the risks facing high-street bookmakers and what the next decade could bring.
Written by and fact-checked by: Stephen Tabone | Last reviewed: 30 October 2026
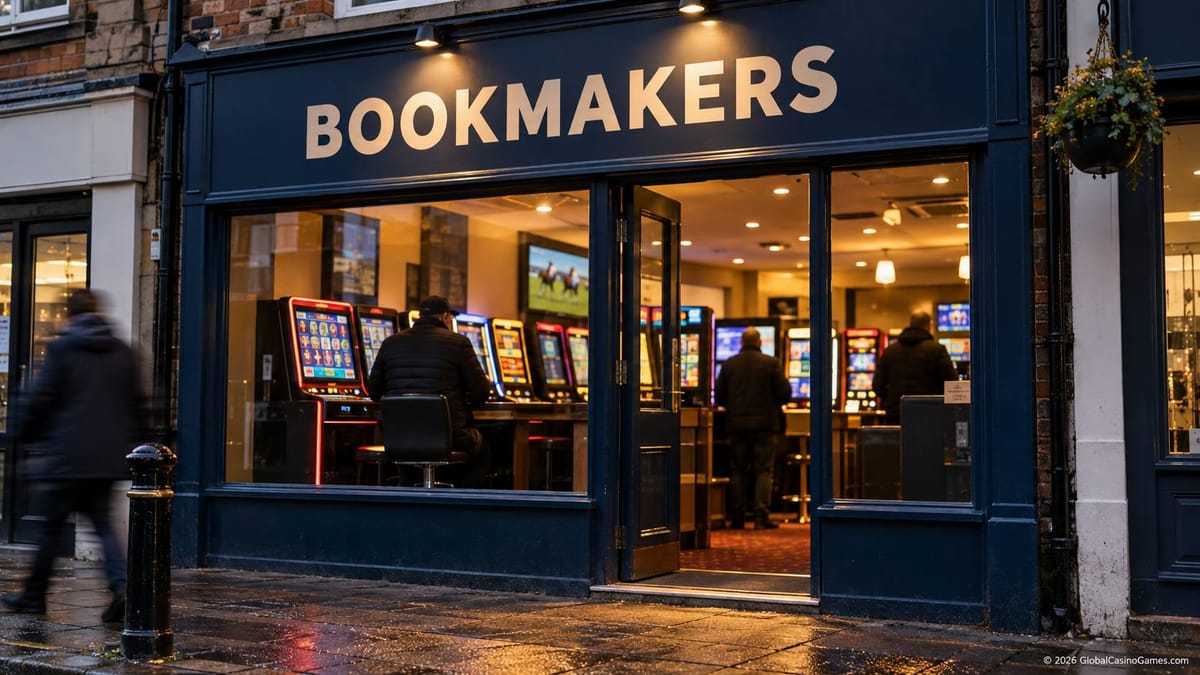
Five percentage points might not sound like much. Yet the latest Budget could make a marginal betting shop less viable.
On 28 October, Chancellor John Healey announced that qualifying gaming machines would move from 20% to 25% Machine Games Duty (MGD) from April 2027. The feared 40% rate did not materialise. But is it modest alongside everything else?
How Much Will the 25% Machine Games Duty Cost Bookmakers?
MGD applies to net machine takings, not the total amount customers stake. From 1 April 2027, the higher 25% rate will cover machines where a game can cost more than £1 or pay more than £100. Some machines already face 25%; the Budget widens the category.
Take £100,000 in annual taxable net takings previously charged at 20%. The duty rises from £20,000 to £25,000. That is £5,000 extra: a 25% increase in duty, not 5%. The shop has £75,000 rather than £80,000 left from those takings before wages, rent and other costs.
The Treasury forecasts £135 million extra in 2027–28, assuming economic responses do not erase the gains.
Why Is a High-Street Gambling Tax Helping Fund High-Street Relief?
Here is the Budget's overlooked irony. The Chancellor explicitly linked the machine-duty rise to support for wider high-street businesses, including a two-year real-terms business-rates freeze for qualifying retail, hospitality and leisure premises.
The Government argues that higher-stake gambling merits heavier taxation. However, betting shops are themselves high-street employers and tenants. Adult gaming centres are also being excluded from specified rates reliefs.
The issue is not whether gambling should contribute to public finances. It is whether taxation intended to support local commerce could make some existing local businesses less viable.
Are Online Gambling Taxes Making the Retail Squeeze Worse?
For omnichannel bookmakers, shops and websites compete for investment.
Remote Gaming Duty jumped from 21% to 40% in April 2026. Most online sports betting is set to move from 15% to 25% in April 2027, although online bets on UK horseracing remain at 15%. Ordinary over-the-counter betting duty is not rising to 40%.
Yet that distinction does not remove the pressure. An operator paying more tax online may reconsider the value of maintaining marginal shops. Conversely, an independent retail-only bookmaker has no digital profits to cushion difficult trading conditions.
I examined the earlier, more severe machine-tax proposal in my analysis of UK bookmakers and Machine Games Duty.
Could the 2028 Tax Reform Reshape Machine Supplier Contracts?
Another change deserves attention. From April 2028, the Government intends to make machine suppliers responsible for MGD when they own machines operated under profit-sharing agreements. Where the premises operator owns the machine or controls takings under a fixed lease, liability generally remains with that operator.
This is a change in who accounts for the duty, not a further announced rate increase.
But moving legal liability need not move the economic burden. Suppliers could negotiate different revenue splits, rental terms or minimum guarantees. Smaller operators may have less bargaining power; larger suppliers may gain an advantage from spreading compliance costs across many machines.
The consultation runs until 20 January 2027. I would watch the contracts, not just the tax rate.
Can Higher Taxes Reduce Gambling Harm Without Weakening Regulation?
There is a reasonable case for taxing higher-risk products more heavily. Additional revenue can support public priorities, and gambling harm is a genuine concern.
There is also a commercial counterargument. When licensed operators face heavier costs, some may reduce investment, promotions or the number of premises. A portion of gambling might disappear, but some customers could move to unlicensed online alternatives. The scale of any such shift should be measured, not assumed.
Pressure extends beyond tax. Financial-risk assessments are being introduced in stages, while campaigners seek tighter football advertising restrictions. University of Bristol researchers estimate that removing gambling logos from shirt fronts reduced live-match gambling messages by only about 10.5%. That supports further scrutiny, although a wider ban remains a proposal, not law.
The question is whether consumer benefits justify the cumulative costs.
What Did the COVID-19 Closures Teach the Industry?
The lockdowns exposed the vulnerability of physical bookmakers. Some operators used the Government's furlough scheme; Entain subsequently announced repayment of £44 million received in 2021. William Hill also repaid its support.
There is no evidence that the latest tax increase is intended as a clawback of pandemic assistance.
The lesson is resilience. Online operators had an alternative channel, although sporting cancellations also hurt betting. A retail-only bookmaker lacked that fallback.
The next disruption may be flooding, a prolonged power failure or another local emergency rather than a pandemic. Would a marginal shop still have the reserves to reopen?
For more on the shrinking retail estate, see my analysis of UK betting shop closures.
Will Gambling Taxes Rise Again Before 2036?
No Chancellor can guarantee five or ten years of stability. The existing framework already allows the Treasury to alter machine stake and prize thresholds, subject to the legal process. A future government could revisit duty rates or the boundary between tax categories. None of that is an announced further increase.
Investors should test stable duties, further increases and weaker footfall alongside rising compliance costs. The impact on machine suppliers, media-rights payments, employment and acquisition valuations could be as important as the direct tax bill.
My view is that the greatest long-term risk is not one five-point increase, but accumulated uncertainty. Large groups can shift capital and renegotiate contracts. Independents generally have fewer choices.
Britain's bookmakers avoided a 40% machine-duty shock in this Budget. Whether they have avoided a decade of contraction is a far more difficult question.